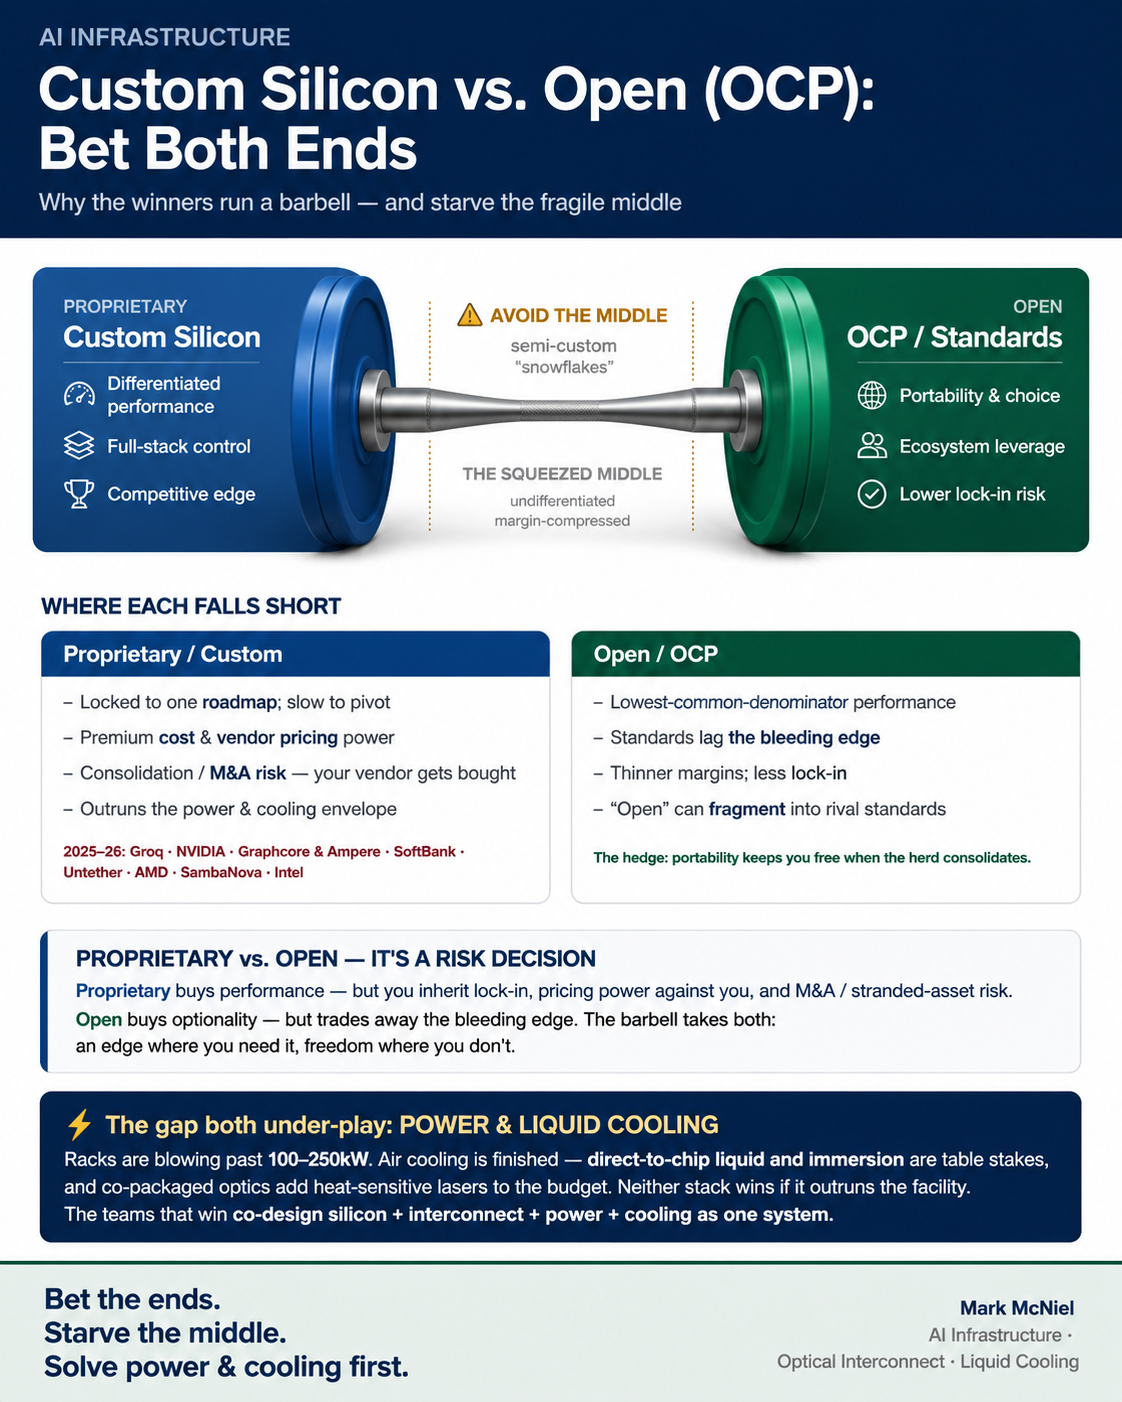
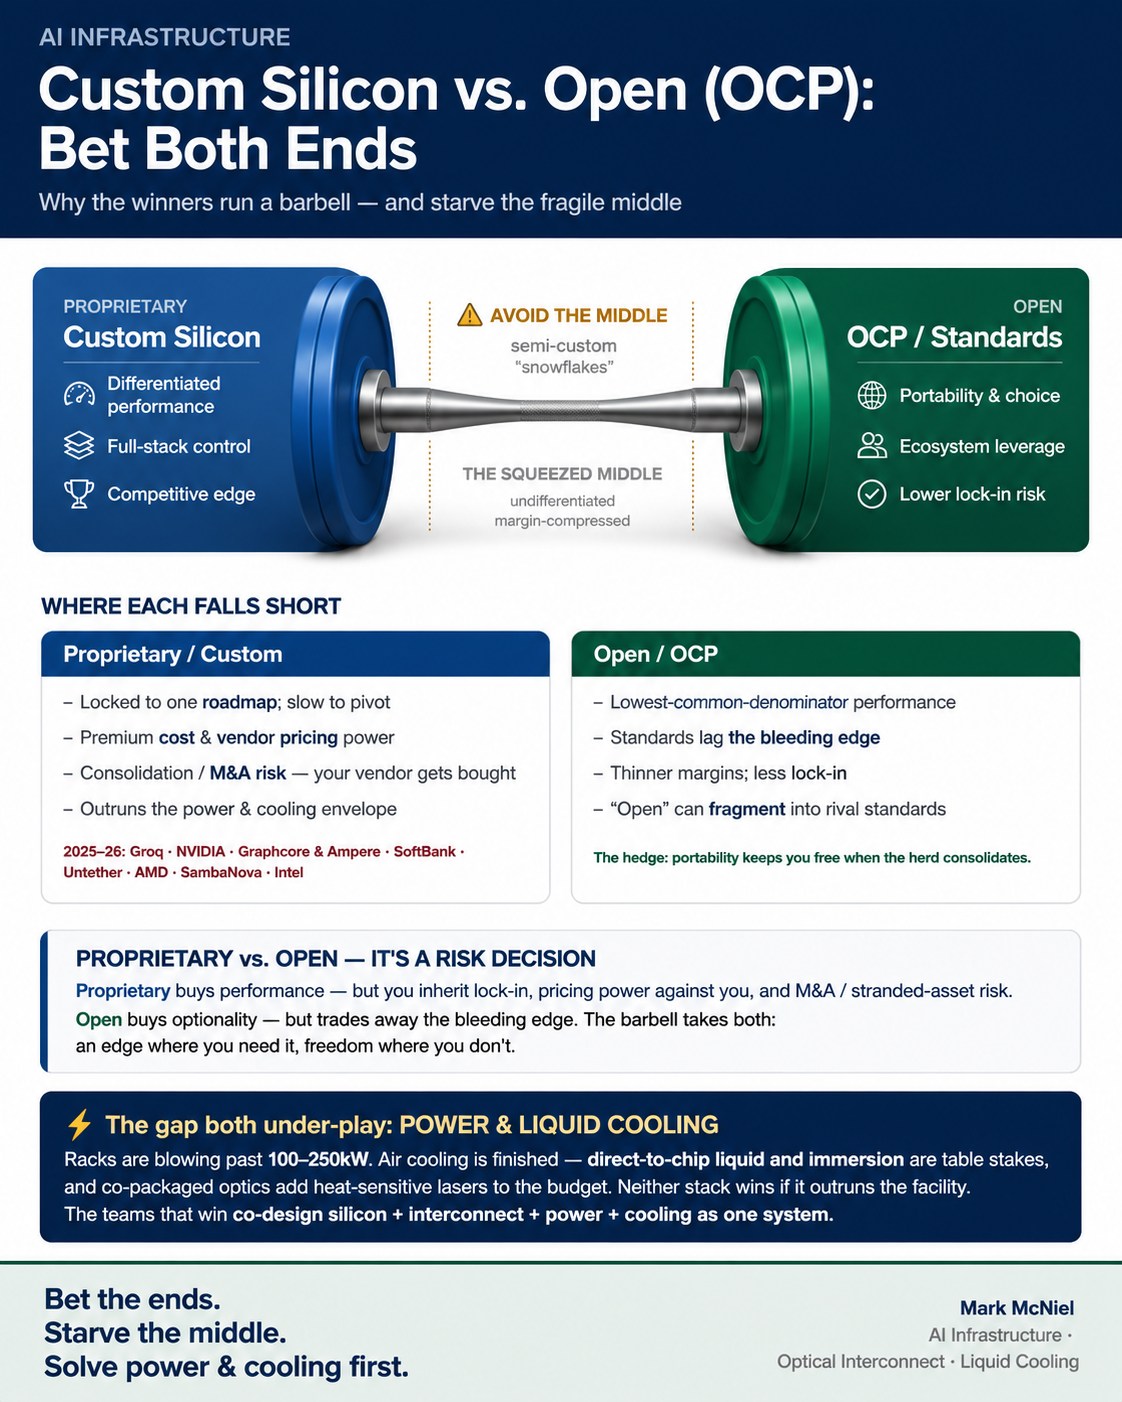
Value is accruing to vertically integrated players and to open-standard specialists. Everything in between is getting compressed, and it is remarkably easy to end up there by accident.
Download the paper (PDF) Download the infographic
There are two places to stand in AI infrastructure right now, and a large uncomfortable space between them.
At one end is vertical integration. Own the silicon, the system, the interconnect and the software, publish the reference architecture, and you capture the whole margin stack. You also capture something more valuable than margin, which is the authority to decide which suppliers exist. When you set the envelope, every other company in the value chain is designing to your document.
At the other end is the open-standard specialist. You are the best available answer to one physics problem, you are trivially integrable into anybody’s design, and you win by being specified rather than by being sold. Your moat is not scale or relationships. It is that replacing you means accepting a worse answer to a problem the customer cannot avoid.
The middle is where most companies actually are: competent, broad-line, differentiated by coverage and relationships rather than by architecture. It gets compressed from above by integrators who set the specification and from below by specialists who own a physics problem. The symptoms are recognizable long before anyone names the cause. Average selling prices flat or declining while volume grows. More bids, longer bids, more of them won on price. A roadmap that has become a list of customer requests. Engineering capacity consumed by variants rather than by advancing a position.
The cooling market ran this pattern in public over about three years. Nearly every independent direct-liquid-cooling specialist of consequence was acquired, and it is worth reading that two ways at once. The specialists had built positions defensible enough to be worth buying, which is the specialist end working. And the acquirers were broad-line industrials paying large multiples to get out of the middle, which is the middle end failing. Both halves of the barbell were visible in the same transaction.
The same structure shows up on the demand side. A hyperscaler designing its own accelerators, its own racks and its own cooling is vertical integration. A neocloud betting the company on one workload profile is a specialist. A regional colocation operator with a general-purpose story, a diversified tenant base and no structural advantage in power or thermal is in the middle, and is currently discovering what that costs when tenants with gigawatt appetites start asking questions about interconnect queues.
What makes the middle dangerous is that you get there through a sequence of individually defensible decisions. Add a product line adjacent to the core, because the customer asked and the engineering is mostly done. Take the high-volume commodity business, because the factory has capacity and the contribution is positive. Hire more coverage rather than resourcing a co-design capability, because coverage shows up in the forecast this quarter and capability shows up in eighteen months. None of those is a mistake in isolation. Taken together over four years they are a strategy, and it is the one nobody chose.
Picking an end costs something real, which is why so few companies do it. Vertical integration requires capital and the willingness to compete with your own customers. Specialization requires refusing revenue, which is much harder than it sounds in a board meeting: turning down adjacent business that would dilute the one thing you are best at, and accepting a smaller addressable market in exchange for pricing power inside it. A company that says it is a specialist while accepting every order that arrives is in the middle.
The test I would apply is a single sentence. Can you name the one physics problem you are the best available answer to, without using the words solutions, platform, or end-to-end? If not, you are in the middle, whatever the strategy document says. And if you can, the follow-up is whether your compensation plan, your engineering roadmap and your hiring pattern all point at that one problem, or at the broad middle your revenue currently comes from.
Moving from the middle toward the specialist end is a two-year operational exercise and it does not start with positioning. It starts with the engineering roadmap, because the only credible specialist claim is a measured one, which means funding the test data that proves your advantage on the specific problem you have chosen and declining the variant requests that would consume the same engineers. Then the target list narrows, usually by more than anyone is comfortable with: a specialist sells into the layer where its problem is decided, which is frequently a shorter list of accounts than the sales organization currently carries. Then compensation has to stop rewarding the revenue you are trying to exit. Companies routinely do the first step and none of the others, which produces a technically excellent company with a sales force still selling breadth.
The investor read of all this is worth knowing if you ever intend to raise or be acquired. Acquirers in this market are not paying for revenue multiples, they are paying for position at the constraint, which is why specialists with modest revenue have been bought at prices that look absurd against their income statements and why broad-line businesses with more revenue have not. If your plan is to be acquired, the asset you are building is a defensible answer to a named problem, and diversifying revenue to look safer actively reduces what you are worth.
The argument against. Barbells are not permanent, and the middle is not worthless. Scale, service coverage, supply reliability and financial durability all live there, and in a supply-constrained year those are worth a great deal of money. A specialist with superior physics, one factory and no second source will lose to an adequate incumbent who can actually ship and can pass a supplier audit. The barbell describes where margin is accruing, not where revenue is. A company can be profitably in the middle for a long time. What it cannot do is be in the middle and also expect the pricing power that belongs to the ends.